The ten day cancellation window, right or practice
By Jose Salloum, Financial Security Advisor (Conseiller en sécurité financière) | October 2026
This article is general education about what the Financial Consumer Agency of Canada, the Autorite des marches financiers and the Civil Code of Quebec publish, read in September 2026. It is not advice. It lists no exclusions, because exclusions belong to contracts, and it does not tell anybody what to declare.
In plain language: this is general education, not a recommendation. What is right for you depends on circumstances we have not seen, and that is what a first conversation is for.
Key Takeaways
- For insurance offered by a lender or a merchant, the AMF states plainly that you can cancel within ten days of purchase at no cost, and that cancellation fees may apply once those ten days have passed.
- For travel insurance, the AMF states that the consumer has ten days to cancel the contract and may ask, within that time, for cancellation at no charge.
- The AMF page on cancelling a life or health insurance contract states no cooling off period, no rescission window, no refund rule and no notification deadline for a contract sold individually. That silence is the finding, not an oversight you can read around.
- On a replacement, the AMF Prior Notice of Policy Replacement form says most insurers allow a ten day period to terminate the new contract without charge. The word most is doing the work there: this is described as insurer practice, not as a statutory right, and the representative must confirm eligibility.
- Insurers may grant longer cancellation periods than the published minimum, so the only period that governs your file is the one written in the documents you were handed.
- A client may terminate the purchase at any time before the contract is issued. Before issue and after issue are two different situations with two different rules.
- When a life insurance contract is replaced, the suicide clause period returns to zero. A period that had already run its course on the old contract starts again on the new one.
Most people believe that any insurance purchase can be undone within ten days. One regulator, the AMF, describes that same ten days in three of its own documents, and describes it differently each time. In one it is stated as a plain entitlement. In another it is stated for travel insurance. In a third it is described as something most insurers allow. And on the AMF page devoted to cancelling a life or health insurance contract, no such period appears at all. The ten days are real in some channels and customary in others. Assuming they are universal is where the trouble starts.
Where the ten days are stated plainly
The clearest statement is in the AMF brochure on insurance offered by lenders or merchants. This is the insurance you are offered at the counter when you borrow, finance a vehicle or buy a durable good. For that channel the AMF states that you can cancel your insurance within ten days of purchase at no cost, and that cancellation fees may apply after the ten days. There is no hedging in the wording and no reference to what an individual insurer may or may not permit.
Two further duties sit alongside it in the same brochure. The distributor must give you an explanatory document, and the distributor must inform you of the refund procedure. Those are the documents that later tell you how the cancellation is actually carried out, who is to be notified and what you get back. The brochure also states that compensation must be revealed where it is more than thirty per cent of the cost of the insurance, which tells you something about why the offer is being made at that counter at that moment.
The brochure adds that insurers may grant longer cancellation periods. Read that as it is written. Ten days is the floor the AMF publishes for this channel, not a ceiling, and the figure that governs your own purchase is the one in your own paperwork. The AMF also notes that special rules apply to travel insurance, which is the next of the three descriptions.
Travel insurance, the same ten days in a different brochure
The AMF brochure on choosing travel insurance states that the consumer has ten days to cancel the contract, and that within that time the consumer may ask for cancellation at no charge. Travel insurance is often bought in a hurry, sometimes days before departure, sometimes as an add on at a counter, so a cancellation period matters more here than almost anywhere else.
The same brochure carries a duty that catches people out. The duty to declare health problems applies both when buying and again when you are about to leave. A declaration that was complete and accurate in June is not necessarily complete and accurate in September. If something changed in between, the duty is engaged a second time.
The brochure then gives an instruction worth following literally: keep a copy of every document requested at the time of purchase, and it names the questionnaire and the medical report, because those documents may be needed in a dispute with the insurer. That advice and the cancellation window point the same direction. What you can prove about the purchase is what you will be able to rely on later. Exclusions in a travel contract work the same way, which is covered in what an exclusion actually says.
The replacement form says most insurers, not all
The third description appears in an AMF form rather than a consumer brochure. The Prior Notice of Policy Replacement is the document a representative completes when a new contract is to take the place of an existing one. On that form, the ten days appear in notably softer language: most insurers allow a ten day period to terminate the new contract without charge.
Most is not all. The form frames the period as something that varies from one insurer to another, and it states that the representative must confirm eligibility. That is the opposite of how a statutory right reads. A right does not need confirming by the person selling you the product, and a regulator does not write most when describing one.
The same form records a separate and firmer point. The client may terminate the purchase at any time before the contract is issued. Before issue, the position is simple. After issue, you are relying either on a published rule for your channel or on what your insurer happens to allow, and those are two very different footings to stand on.
The page on cancelling says nothing about a free look
The AMF maintains a page titled for cancelling a life or health insurance contract. If a universal ten day free look existed for individually sold life and health insurance, that page is where you would expect to find it. It is not there. The page states no cooling off period, no rescission window, no refund rule and no notification deadline for such a contract.
Silence in an official source is not permission to assume the generous reading. It is a finding. On the AMF own page on the subject, the ten days that a reader believes to be universal are simply absent, and they are absent in the one place a reader would look first.
What the page does state is different and well known: the two year incontestable clause, treated at more length in the two year contestability period. It also states one thing about replacements that belongs in its own section below, because it is the sharpest fact on this page and the one most easily missed.
A worked situation: two purchases, two different footings
Imagine Daniel, who in the same month does two things. He finances a car and accepts the insurance offered at the dealership counter. Three weeks later he signs an individually sold life insurance contract through a representative. Both make him uneasy afterwards, and he looks for the ten days he assumes applies to each.
For the dealership purchase, the AMF publishes the position for that channel: cancellation within ten days of purchase at no cost, with the distributor obliged to have given him an explanatory document and to have informed him of the refund procedure. He has the document in the glove compartment, dated. He knows where he stands.
For the individually sold contract, there is no such published period. The AMF page on cancelling a life or health insurance contract states none, and the AMF replacement form describes the ten days as what most insurers allow. Daniel is not without options; he is without a published rule. What governs him is the wording of his own contract and his own insurer practice, neither of which he asked to see in writing on the day. Had he asked one question at the point of purchase, the two files would have looked the same. They do not.
On a replacement, the suicide clause returns to zero
The AMF states that the suicide clause period returns to zero when a life insurance contract is replaced. A life insurance contract typically limits what is payable if death is by suicide within a defined early period of the contract. That period runs from the start of the contract and, once it has run, it has run.
A replacement restarts it. A contract that had been in force for years, with that period long behind it, is cancelled, and a new contract begins with the clock back at zero. Nothing about the insured person changed. The protection against that clause, which had been fully earned, is gone, and it is gone from the day the new contract begins.
This is harsh, and it is harsh in a particular way: nobody feels it at the moment of signing. It costs nothing, changes no premium and triggers no warning on a statement. It surfaces only in the one circumstance in which the family can least afford it. It is a reason to read a Prior Notice of Policy Replacement rather than initial it, and it belongs beside the other quiet mechanics set out in what undoes a policy.
What to ask for, in writing, before you sign
Because the ten days are published for some channels and customary in others, the practical step is the same everywhere: get the cancellation terms in writing at the point of purchase, before signing. Ask what the cancellation period is for this contract, ask who must be notified, and ask what is refunded. If the answer is given out loud, ask for it on paper or in an email.
Keep the explanatory document. Where the distributor is a lender or a merchant, the AMF requires it to be given to you and requires the refund procedure to be explained. That document is the evidence of what you were told, and it is what you will be reading on day eight if you change your mind.
Note the date of purchase, and keep whatever proves it. Every version of the ten days runs from a date somebody has to be able to establish, and the AMF does not publish what proof you must hold. A dated email, a signed copy with the date visible, a receipt: any of these is better than a recollection. If a cancellation is later refused, the route of recourse is described in how to complain and to whom.
This practice explains published rules; it does not interpret your contract for you and does not give legal advice. Where the question is what a contract clause means or what rights it creates, that is a question for a lawyer or a notary.
Sources
- Autorite des marches financiers, Insurance offered by lenders or merchants (brochure), read 1 October 2026, https://lautorite.qc.ca/fileadmin/lautorite/grand_public/publications/consommateurs/assurance/assurances-preteurs-commercants_an.pdf
- Autorite des marches financiers, Choosing Travel Insurance (brochure), read 1 October 2026, https://lautorite.qc.ca/fileadmin/lautorite/grand_public/publications/consommateurs/assurance/assurance-voyage_an.pdf
- Autorite des marches financiers, Prior Notice of Policy Replacement (form), read 1 October 2026, https://lautorite.qc.ca/fileadmin/lautorite/formulaires/professionnels/assureurs/preavis-remplacement-contrat-assurance-personnes_an.pdf
- Autorite des marches financiers, Cancelling a life or health insurance contract, read 1 October 2026, https://lautorite.qc.ca/en/general-public/insurance/cancelling-a-life-or-health-insurance-contract
Frequently Asked Questions
Is there a ten day free look on every insurance purchase in Quebec?
No. The AMF states a ten day cancellation at no cost for insurance offered by a lender or a merchant, and ten days for travel insurance. For an individually sold life or health contract, the AMF page on cancelling one states no cooling off period, no rescission window and no refund rule. Treat the ten days as channel specific and confirm it for your own contract.
Does the AMF say the ten days are a right or an insurer practice?
Both, depending on the document. The brochures on lender and merchant insurance and on travel insurance state the ten days plainly. The Prior Notice of Policy Replacement form says most insurers allow a ten day period to terminate the new contract without charge, and adds that the representative must confirm eligibility. The two framings sit side by side in the same regulator publications and are not reconciled.
Can I cancel before the contract has even been issued?
The AMF Prior Notice of Policy Replacement form states that the client may terminate the purchase at any time before the contract is issued. Before issue and after issue are distinct situations. After issue, you rely on the published rule for your channel if there is one, or on the cancellation terms written into your own contract.
Why does replacing a life insurance contract matter so much?
Because the AMF states that the suicide clause period returns to zero when a life insurance contract is replaced. An early period that had already run its course on the old contract starts again on the new one, from the day the new contract begins. Nothing on a premium notice or a statement will tell you this happened.
What should I keep from the day of purchase?
The explanatory document, anything stating the cancellation terms and refund procedure, and proof of the purchase date. The AMF travel brochure says to keep a copy of every document requested at purchase, naming the questionnaire and the medical report, because they may be needed in a dispute with the insurer. The same habit serves you on a cancellation.
Do the ten days ever run longer?
The AMF brochure on insurance offered by lenders or merchants states that insurers may grant longer cancellation periods. Ten days is the published floor for that channel, not a maximum. How much longer an insurer may allow is not published, which is one more reason to get the period for your own contract in writing before signing.
A thirty-minute discovery meeting
A first conversation establishes whether this fits. No illustration is prepared and nothing is arranged.
Often the answer is no, and you will hear it during the call rather than in a proposal afterwards.
The form is on the discovery meeting page and takes a minute. It arranges a conversation. It is not advice, and nothing is being sold here.
Listen to this page
Read aloud by your own browser. Nothing is sent anywhere.
About the author
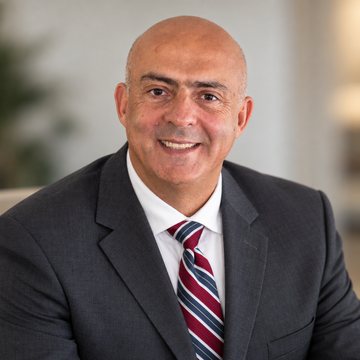
Jose Salloum is a Financial Security Advisor (Conseiller en sécurité financière) licensed by the Autorité des marchés financiers in Quebec, by the Financial Services Regulatory Authority of Ontario, and by the Insurance Council of British Columbia. Licensed since 2001, he works with Canadian families, business owners and incorporated professionals.
He is the founder of Canadian Wealth Creation Centre Inc. (CWCC), registered with the AMF, and of its educational branch IBCFinancial.com. He holds the Infinite Banking Concepts® Authorized Practitioner certification from the Nelson Nash Institute, a private certification rather than a regulatory licence.
CWCC is not registered with CIRO and does not provide securities advice. This page is general education and not advice on any individual file.
Important disclosures
This page is education, not advice. The content is general information prepared by Canadian Wealth Creation Centre Inc. It does not take your circumstances into account and is not a recommendation to buy, hold or cancel any contract. CWCC is not registered with CIRO and does not provide securities advice. The firm places insurance in Quebec, Ontario, Alberta, British Columbia, Manitoba and New Brunswick; clients elsewhere are served by advisors licensed in their province.
Nothing here was written with your file in front of us. Read it to understand the subject, then judge it against your own situation, ideally with someone who is licensed where you live and who has seen your numbers.
This is not tax advice, and the tax treatment depends on your own circumstances. The tax treatment described depends on the contract remaining exempt under the Income Tax Regulations and on the reader’s individual circumstances. A withdrawal, a surrender or a policy loan may be a disposition under the Income Tax Act, and amounts above the adjusted cost basis may be taxable in the year they occur. Tax rules change. Canadian Wealth Creation Centre Inc. is licensed in life and health insurance. It is not an accounting practice, it does not prepare returns, and nothing on this site is tax advice or an opinion on any reader’s tax position. Anything a reader intends to rely on should be confirmed with a professional accountant and against the current published rule of the Canada Revenue Agency and, in Quebec, Revenu Québec.
The tax result is not automatic and it is not unconditional. It rests on the contract staying within the Canadian rules and on your own situation. Before you rely on any of it, talk to an accountant who has actually worked with these contracts.
Illustrations and projections are not predictions. Any figures, examples or illustrated values are hypothetical, are shown to explain a mechanism, and are not a forecast of the performance of any contract. Actual values will differ and may be lower than those shown. Past dividend scales do not predict future scales.
An example is there to show how the parts move, not to tell you what you will get. Any real illustration you are shown should be read on its guaranteed columns first.